Are you ready to make smart choices with credit—and avoid the costly mistakes that trip up so many first-time borrowers?
In this quiz, you’ll put your knowledge to the test on the essentials of using credit: what impacts your credit score, how debt works, what your rights are, and how credit decisions can shape your financial future.
A single missed or late payment can drop your credit score by up to 100 points and stay on your record for seven years!
The percentage of your available credit currently being used. A ratio above 30% can negatively impact your credit score.
Debt backed by collateral (like a car or house) that the lender can repossess if the borrower defaults on payments.
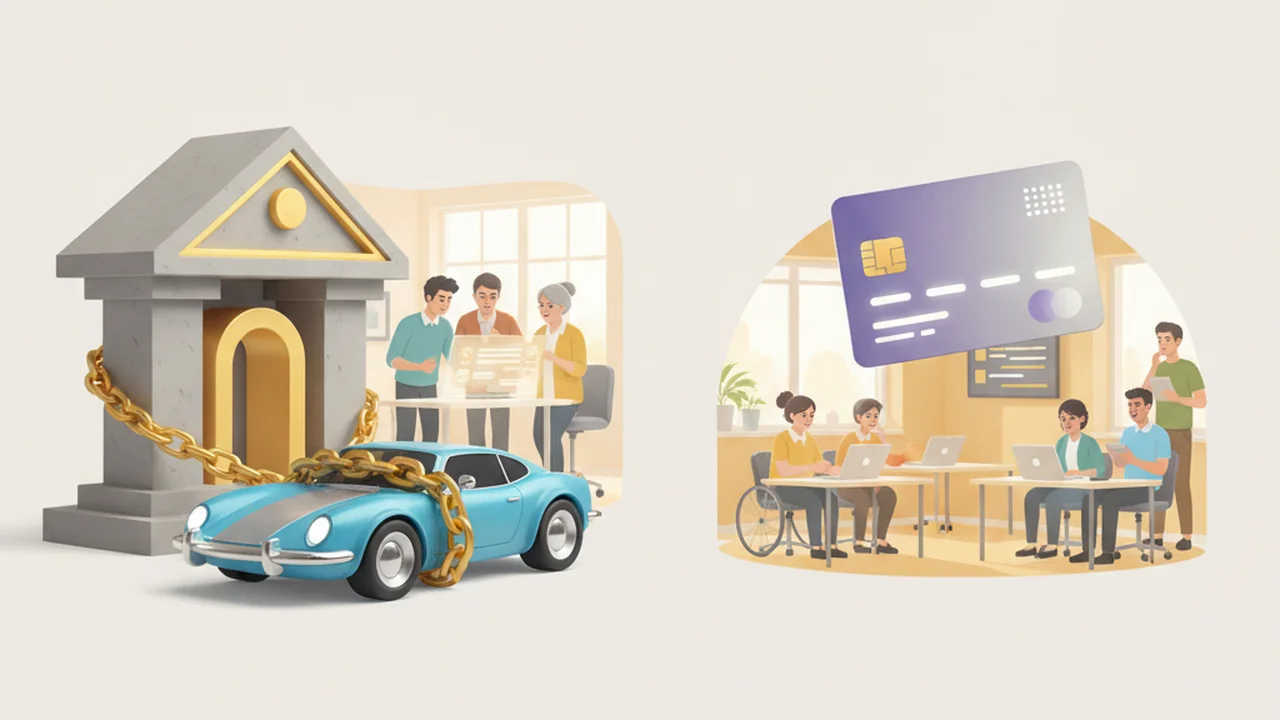
What is the PRIMARY difference between using a credit card and a debit card for purchases?
Which factor has the LARGEST impact on your FICO credit score?
Devon is comparing two auto loans: Loan A with 5% APR and Loan B with 10% APR. Over 60 months, how much MORE will Devon pay in total for Loan B compared to Loan A?
Maria charges $1,500 to a credit card with 21% APR and makes $50 minimum payments. About how long will it take to pay off, and how much will she pay in total?
Which of the following is an example of SECURED debt?
Taylor has a credit card with a $2,000 limit and a $1,400 balance. What is Taylor’s credit utilization ratio, and how might this affect their credit score?
Jordan has a gross monthly income of $4,000 and monthly debt payments totaling $700. What is Jordan’s debt-to-income (DTI) ratio?
What is the ONLY official website where you can get free credit reports from all three credit bureaus?
Under the Fair Debt Collection Practices Act (FDCPA), which of these actions by a debt collector is ILLEGAL?
Which of the following is a PRIMARY responsibility of credit card users?
Applying for your first car loan? The APR you accept can make a two-thousand dollar difference on a $15,000 car—even if your monthly payment only changes by $36!
Practicing good credit habits now—like paying on time and keeping balances low—can mean lower interest rates and easier approvals when you need a loan later.
Want to go deeper? The science behind credit scores
Credit scores are calculated using complex algorithms, but the main components are standardized: payment history (35%), amounts owed (30%), length of credit history (15%), new credit (10%), and credit mix (10%). Lenders use these scores to predict how likely you are to repay debt responsibly.
Practice calculating your credit utilization ratio using these steps (use a hypothetical or real card if you have one):
- Write down your current credit card balance and your card’s credit limit.
- Divide your balance by your credit limit and multiply by 100 to find the utilization percentage.
- Is your utilization under 30%? If not, how could you reduce it?
How might a high credit utilization ratio impact your ability to get a loan or a lower interest rate?
Why is it important to regularly check your credit report from the official source?
What practices can help you avoid falling into the “minimum payment trap” with credit cards?
Project: Hold a Credit Case Conference
Course Driving Question: How can I build a realistic 10-year financial plan for my life after high school that can survive real-world trade-offs, setbacks, and opportunities?
Your project move: Defend how your plan uses—or avoids—credit while keeping debt manageable.
- Present your credit-building, borrowing, and repayment choices in two minutes.
- Answer one peer question about total cost, DTI, utilization, or borrower rights.
- Use quiz evidence to revise one choice or add one protection.
Add to your Missouri Money Map: A one-page Credit Strategy with limits, safeguards, and a revised decision.
Your reviewer records one strength, one risk, and one evidence-based recommendation.
Think about a time (real or hypothetical) when you or someone you know used credit. What choices led to positive or negative outcomes? What would you do differently next time, based on what you’ve learned in Unit 5?
Paying just the minimum payment on your credit card is a smart way to avoid debt and interest.
Minimum payments keep you in debt longer and dramatically increase the total cost due to interest—always pay more than the minimum if you can.
“Credit cards and debit cards may look alike, but they function very differently—and choosing the wrong one in the wrong situation can be costly.”
Your credit decisions today—like making payments on time and understanding your credit utilization—directly impact your borrowing power and financial future.
Knowing your rights and responsibilities as a borrower helps you avoid scams, unnecessary fees, and costly mistakes with credit.
- Credit score factors like payment history and utilization are the most important for your financial health.
- Secured loans use assets as collateral; unsecured loans do not.
- Always use the official site—AnnualCreditReport.com—to check your credit for free.
The Shift
- Credit is a powerful tool—when used wisely, it opens financial doors, but misused, it creates lasting setbacks.
- Understanding key metrics like APR, credit utilization, and DTI helps you avoid debt traps and build a strong financial future.
- Protecting your credit rights and practicing responsible borrowing are essential skills for adulthood—start now!