How can a small monthly insurance payment protect you from life-altering financial setbacks?
Imagine two Missouri families facing tragedy—one is able to keep their home, their kids in the same schools, and their dreams for the future. The other loses not just a loved one, but financial stability and opportunity. What made the difference? Smart insurance decisions. This lesson shows you how to protect everything you’ve worked for by understanding risk and using insurance wisely.
The $800,000 Mistake: A Tale of Two Missouri Families
The Martinez Family (Kansas City) had $500,000 in life insurance. When tragedy struck, that coverage meant their finances stayed stable—they paid off the mortgage, set aside college money, and kept their life on track despite emotional loss.
The Thompson Family (Springfield) had just $50,000 in coverage. When disaster hit, they lost their home, changed schools, and faced constant financial stress. The so-called “savings” from a lower premium cost them $450,000 and upended their lives.
Insurance isn’t just a bill—it’s your safety net when the worst happens.
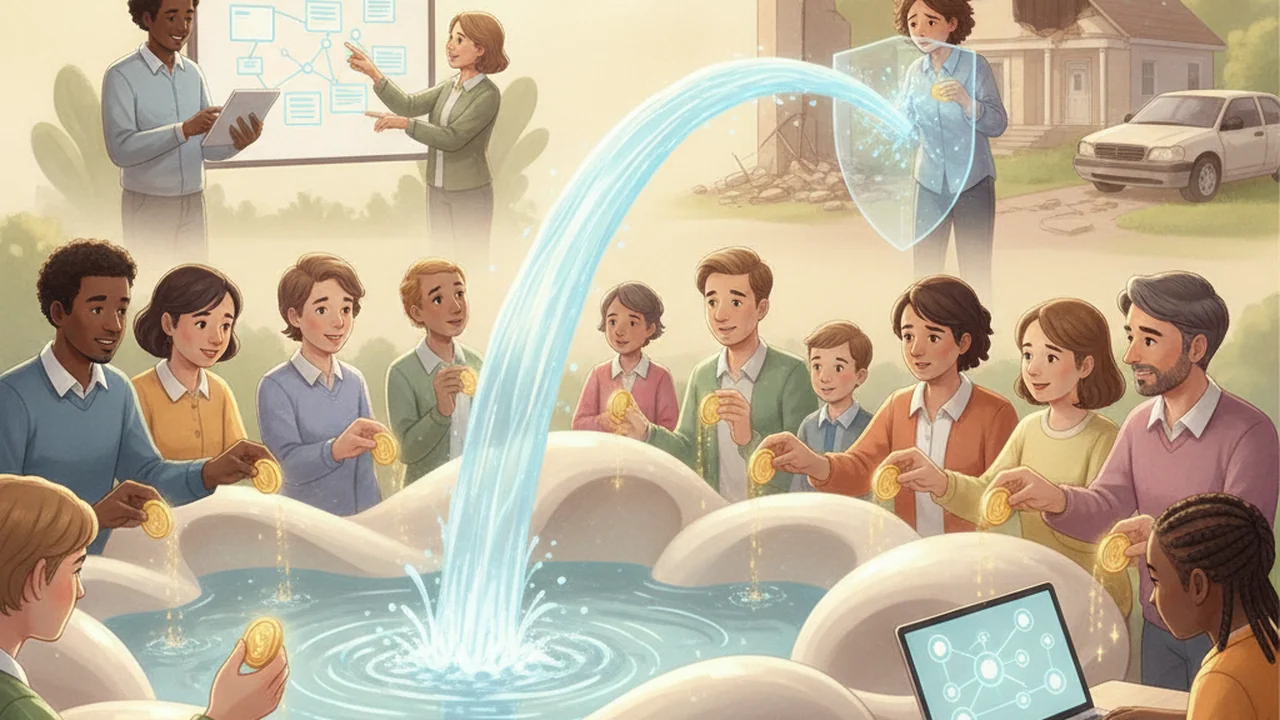
Insurance transfers financial risk. It costs relatively little but protects against catastrophic financial losses.
Paying a small insurance premium now can prevent devastating financial losses later—protecting not just your savings, but your future.
- Learned how insurance can make a life-changing difference for families.
- Understand the kinds of risks insurance helps manage.
Imagine you’re responsible for your own rent, car, and expenses. What financial risks would worry you most?
Understanding Financial Risks
Financial risk means the possibility of losing money or facing unexpected financial burdens. These risks are part of everyday life, and insurance exists to help you manage them.
- Death Risk: Loss of family income, funeral costs, unpaid debts.
- Health Risk: Medical bills, lost wages, long-term care.
- Disability Risk: Income loss if you can’t work, need for home or vehicle changes.
- Property Risk: House or car damage, theft, natural disasters.
- Liability Risk: Being sued for injury or damage, legal fees, court judgments.
Recognizing your risks is the first step to protecting your finances.
In Missouri, about 15% of drivers are uninsured. If you’re hit by one, having Uninsured Motorist coverage can save you from huge bills.
Many Missouri college students face high medical bills after car accidents. Without insurance, even a “minor” crash can mean thousands in debt before graduation.
How would your life change if you suddenly faced a $10,000 medical bill or lost your laptop to theft?
Strategies for handling the possibility of financial loss, including avoiding, reducing, accepting, or transferring risk (usually through insurance).
Want to go deeper? How insurance companies set premiums
Insurance companies use complex math called “actuarial science” to analyze data and predict how likely different risks are. They combine statistics about age, driving history, health, and even weather patterns to decide how much each customer should pay in premiums. The goal is to collect enough to pay claims and stay profitable—while remaining affordable for most people.
How Insurance Works
Insurance is a contract: you pay regular premiums, and if something bad happens (like a car accident or house fire), the insurer pays for covered losses. By pooling money from many customers, insurance companies spread the risk—so a few big accidents don’t ruin anyone’s finances.
- Policyholder: You (the person/family buying insurance)
- Insurer: The insurance company
- Premium: Your payment (monthly/annual cost for coverage)
- Claim: Request for the insurance company to pay you for a covered loss
- Beneficiary: Person who receives payment (life insurance)
When you buy insurance, you’re paying to transfer a big risk you can’t afford, in exchange for a small, predictable cost.
The amount you pay for insurance coverage, usually monthly or annually. Factors like age, location, and risk level affect your premium.
Insurance agents in Missouri recommend reviewing your policies every year—especially if you move, buy a car, or your family changes. Small changes can have a big impact on your premiums and coverage.
Why do you think insurance companies charge different premiums to different people?
Key Insurance Terms You Need to Know
- Deductible: What you pay before insurance starts covering costs. Higher deductibles usually mean lower premiums.
- Coverage Limit: The most your insurance will pay for a covered loss.
- Copay: Flat fee you pay for certain services (like a doctor visit).
- Coinsurance: The percentage of costs you pay after meeting your deductible.
- Out-of-Pocket Maximum: The most you could pay in one year. After that, insurance covers 100% of costs.
- Exclusions: Things the policy doesn’t cover (e.g., flood damage on most homeowners policies).
- Rider: An add-on that covers something extra, like expensive jewelry or rental cars.
Insurance is a waste of money if you don’t file a claim—you’re just throwing cash away.
Insurance protects you from rare but catastrophic losses. The peace of mind—and financial security—are worth much more than the cost if disaster strikes.
What is a deductible?
Tap to revealThe amount you pay out of pocket before your insurance covers the rest of a loss or claim.
Define “premium” in insurance.
Tap to revealThe regular payment you make to keep your insurance coverage active.
What does “exclusion” mean in an insurance policy?
Tap to revealSpecific risks or losses that your policy does not cover; these are listed in the insurance contract.
What Affects Your Insurance Premium?
Insurance companies look at many things to decide your premium. The exact factors depend on the type of insurance:
- Auto: Age, driving record, location (city/rural), credit score, car type, annual mileage.
- Health: Age, tobacco use, number of dependents, plan type.
- Life: Age, health, tobacco use, coverage amount, job/hobbies.
- Homeowners: Home value, location, construction, claims history, security systems.
For example, young drivers in St. Louis or Kansas City usually pay more for car insurance because statistics show more accidents in those cities. Smokers pay much more for life and health insurance. Living in a tornado-prone area like Joplin can raise home insurance costs.
Try to predict your own auto insurance cost using these common factors:
- Write down your age, gender, city/town, and the car you would drive.
- Would you have a clean driving record, or any tickets/accidents?
- Search for a real Missouri insurance quote online (try a site like ValuePenguin Missouri Auto Insurance).
- Was your estimate close to the quote? What factors increased or decreased your rate?
Types of Insurance You Need to Know
- Auto Insurance: Required by Missouri law; pays for injuries and damages in car accidents.
- Health Insurance: Pays medical bills for illness or injury. Catastrophic medical costs can ruin finances without it.
- Homeowners/Renters Insurance: Protects your property from fire, theft, storms, and more.
- Life Insurance: Provides money for your family if you die (pays off debts, replaces income, funds education).
- Disability Insurance: Pays part of your income if you can’t work due to illness or injury.
Some insurance is required (auto), some is strongly recommended (health, renters), and others may depend on your situation (life, disability).
Of all the types of insurance, which do you think is most important for someone your age—and why?
Project: Build a Risk-Protection Plan
Course Driving Question: How can I build a realistic 10-year financial plan for my life after high school that can survive real-world trade-offs, setbacks, and opportunities?
Your project move: Choose insurance coverage that protects your Launch Profile from losses it could not comfortably absorb.
- List major risks involving health, transportation, housing, property, income, and dependents as applicable.
- Choose needed policy types and compare premium, deductible, limits, exclusions, and legal minimums.
- Explain one risk you will retain and one you will transfer to an insurer.
Add to your Missouri Money Map: An insurance coverage table and a monthly premium line added to the budget.
Ask a partner to test the plan with one loss scenario and identify any coverage gap.
Think about a time when you, your family, or someone you know faced an unexpected event—like a car accident, major illness, or theft. How did insurance (or not having insurance) impact their situation? What would you do differently now that you understand how insurance works?
Missouri standard PF.VI.1.E: Comparing Health Insurance Options and Preventive Care
Health insurance pays medical bills when you are sick or hurt, and it also pays for care that keeps you well. Choosing a plan means comparing networks, monthly premiums and what you pay when you get care.
Common plan types (HealthCare.gov, Health insurance plan types)
- HMO: usually limits coverage to doctors who work for or contract with the HMO; it generally won’t cover out-of-network care except in an emergency.
- PPO: you can see doctors outside the network without a referral, for an additional cost.
- EPO: covers only in-network care, except in an emergency.
- HDHP with an HSA: a higher deductible before the plan pays. For 2026 an HSA-eligible plan has a self-only deductible of at least $1,700 and out-of-pocket maximum of no more than $8,500. An HSA lets you set aside pre-tax money for medical costs, and the balance rolls over year to year (HealthCare.gov, HSA-eligible plans).
Preventive care: most plans cover services such as blood pressure checks, depression screening, flu shots and HIV testing (ages 15 to 65) at no cost to you, even before you meet your deductible, when you use an in-network provider (HealthCare.gov, Preventive health services).
Worked example: two plans, two kinds of years (illustrative)
| Plan A (PPO) | Plan B (HDHP) | |
|---|---|---|
| Premium | $300/month = $3,600/year | $180/month = $2,160/year |
| Deductible / coinsurance | $1,000 / 20% | $3,000 / 20% |
| Out-of-pocket maximum | $4,000 | $6,000 |
| Healthy year: checkup + flu shot, in-network | $3,600 + $0 = $3,600 | $2,160 + $0 = $2,160 |
| $12,000 hospital bill | $1,000 + 0.20 × $11,000 = $3,200; total $6,800 | $3,000 + 0.20 × $9,000 = $4,800; total $6,960 |
In a healthy year the HDHP saves $1,440, and preventive visits cost $0 on both plans. In the bad year, Plan A costs $160 less. If you put the $1,440 premium savings into an HSA, that money would be there, pre-tax, for the next big bill.
Work these on your own, then open each answer to check yourself.
Which plan type generally will not pay for an out-of-network doctor except in an emergency: HMO or PPO?
Check your answer
HMO (EPOs work this way too). A PPO pays for out-of-network care at an additional cost.
Illustrative: a plan has a $2,000 deductible, 30% coinsurance and a $5,000 out-of-pocket maximum. You have an $8,000 bill. What do you pay?
Check your answer
$2,000 + 0.30 × ($8,000 − $2,000) = $2,000 + $1,800 = $3,800, which is under the $5,000 maximum, so $3,800.
You have not met your deductible. You get a flu shot from an in-network provider. What do you usually pay?
Check your answer
Usually $0: preventive services like flu shots are covered without cost-sharing in-network, even before the deductible.
Which type of insurance is required by law for all drivers in Missouri?
Insurance is a critical part of your personal financial plan—protecting you from events that could otherwise ruin your finances or your future.
How confident are you that you can explain how insurance transfers financial risk?
The Shift
- Insurance helps you manage risk by turning unpredictable disasters into manageable monthly costs.
- Understanding insurance terms and types lets you make smart, informed financial decisions.
- Choosing the right insurance can protect your future, your family, and your dreams.