How can your choice of financial institution impact your money, your goals, and your future opportunities?
Imagine receiving your very first paycheck—a big step toward independence. But what happens next? Where should you put your money so it’s safe, accessible, and working for you, not just sitting still or vanishing in fees?
Jordan, a recent high school grad in Missouri, just landed a full-time job and picked up their first paycheck: $1,847.32. They face a decision—visit a check-cashing store and lose $55 in fees, open a big bank account but risk monthly charges, or join a local credit union with limited locations. What would you do?
What matters most to you when choosing where to keep your money: convenience, low fees, personal service, or something else?
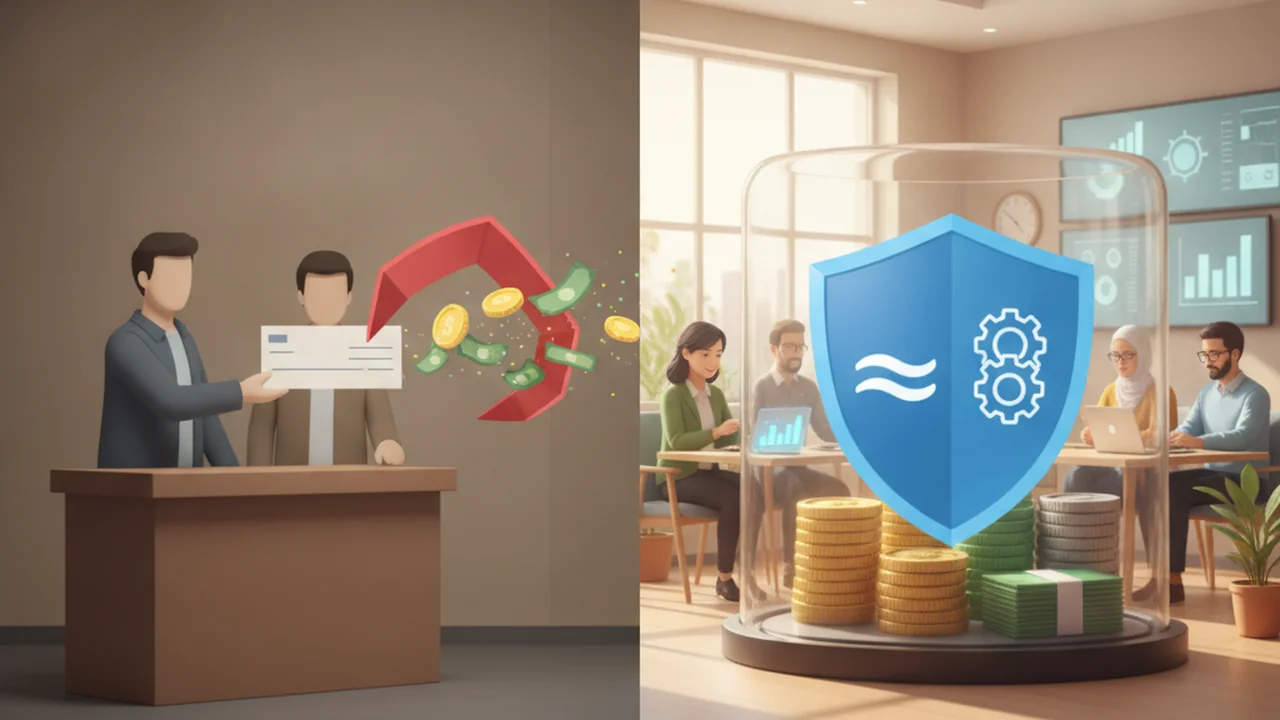
About 7% of U.S. households are “unbanked”—they don’t have a checking or savings account. That means millions rely on costly alternatives like check-cashing stores and miss out on the benefits and protections of banks and credit unions.
An organization that handles money transactions, offers accounts for savings and checking, and provides other financial services.
Federal government insurance programs that protect your money (up to $250,000 per depositor) if a bank (FDIC) or credit union (NCUA) fails.
Many Missouri teens open their first checking or savings account at a local credit union for summer job paychecks. Others choose digital-only banks for higher interest rates and no fees—especially if they rarely use cash.
Types of Financial Institutions
Commercial Banks
- For-profit, owned by shareholders (e.g., Bank of America, Wells Fargo, UMB Bank)
- Wide range of services, lots of locations and ATMs
- FDIC insured, but often charge higher fees and pay lower savings rates
Credit Unions
- Not-for-profit, member-owned (e.g., Missouri Credit Union, Alltru Credit Union)
- Lower fees, better savings rates, but fewer branches
- NCUA insured; membership based on location, employer, or family
Online Banks
- No physical branches (e.g., Ally, Chime, SoFi)
- Lowest fees, highest savings rates, great mobile apps
- FDIC insured; cash deposits can be tricky
Check-Cashing Stores
- Charge 1–5% to cash checks—costing hundreds a year
- No insurance or savings, and can be predatory
“Banks are the only safe place to keep your money, and all of them are basically the same.”
Credit unions and online banks can be just as safe (thanks to NCUA and FDIC insurance) and often offer better rates, lower fees, and more personal service—if you know what to look for.
What does FDIC insurance do?
Tap to revealIt protects your money (up to $250,000) in case a bank fails, guaranteeing you won’t lose your insured deposits.
Name one main advantage of credit unions over traditional banks.
Tap to revealCredit unions typically offer lower fees and better interest rates on savings accounts and loans.
What is a major drawback of check-cashing stores?
Tap to revealThey charge high fees (1–5%) just to access your money and provide no insurance or savings options.
Want to go deeper? Why do banks and credit unions require a minimum balance?
Minimum balances help cover the cost of maintaining accounts. Banks, as for-profit businesses, use minimums to ensure accounts are profitable. Credit unions, being not-for-profit, often have lower or no minimums because they return profits to members through better rates and lower fees.
How much does it really cost to cash your check at a store versus depositing it in a checking account?
- Calculate the fee for cashing a $1,000 check at a check-cashing store (use 3%).
- Compare this to the cost of depositing the same check into a fee-free credit union or online bank account.
- Multiply the check-cashing fee by 26 (for a full year of biweekly paychecks). How much could you save in a year by choosing a checking account?
Why might someone choose a check-cashing store even though it costs more than a bank or credit union?
Practitioners say: “Teens who start with credit unions often stick with them for years, benefiting from fewer fees and higher savings rates—especially when they’re just starting out.”
If you needed to deposit cash or get help with your account, would you prefer a local branch you could visit or is doing everything online enough for you?
Project: Select Your Financial Team
Course Driving Question: How can I build a realistic 10-year financial plan for my life after high school that can survive real-world trade-offs, setbacks, and opportunities?
Your project move: Choose accounts and services that fit your Launch Profile’s daily money needs and goals.
- Compare at least one bank, one credit union, and one online option using fees, access, rates, tools, and deposit insurance.
- Score each institution with a weighted comparison table.
- Choose checking and savings options and explain one feature you rejected.
Add to your Missouri Money Map: A cited institution scorecard and account recommendation.
Have a partner test your choice against an ATM problem, overdraft, or lost-phone scenario.
Think about a time you or someone you know needed to access money quickly. How did the choice of financial institution (or lack of one) affect the situation? What would you do differently now?
Credit unions are insured by the , which protects your deposits just like the FDIC does for banks.
- You can describe the main differences between banks, credit unions, and online banks.
- You know how fees and interest rates impact your bottom line.
“Choosing where your money lives is one of your first important financial decisions.”
Your choice of financial institution can save—or cost—you hundreds of dollars each year in fees and lost interest, so it pays to compare your options carefully.
FDIC and NCUA insurance mean your money is protected at reputable banks and credit unions—don’t risk using unprotected services for the sake of convenience.
How confident are you that you can compare bank, credit union, and online bank features to make the best choice for your needs?
The Shift
- Not all financial institutions are created equal—comparing fees, interest, and services helps you keep more of your money.
- FDIC and NCUA insurance protect your deposits, but check-cashing stores do not.
- Your financial choices today set up your ability to save, build credit, and avoid unnecessary costs in the future.
Missouri standard PF.III.4.B: Calculating Your Account Balance
Your bank app shows a balance, but it may not include transactions that have not finished processing yet. Keeping your own transaction register (a running list of every deposit and withdrawal) lets you know exactly what you can spend and catch errors or fraud quickly.
Money added to your account: paychecks, cash you put in, transfers in. Add it.
Money taken out: ATM cash, debit card purchases, checks you wrote, automatic payments, fees. Subtract it.
Worked example: Jordan’s register (illustrative)
| Date | Description | Withdrawal (−) | Deposit (+) | Balance |
|---|---|---|---|---|
| 11/1 | Starting balance | $412.50 | ||
| 11/1 | Debit card: gas | $38.75 | $373.75 | |
| 11/3 | Paycheck (direct deposit) | $623.40 | $997.15 | |
| 11/5 | ATM withdrawal | $60.00 | $937.15 | |
| 11/8 | Check #101: rent share | $350.00 | $587.15 | |
| 11/10 | Cash gift deposited | $50.00 | $637.15 | |
| 11/12 | Automatic payment: music app | $15.99 | $621.16 |
Each line: previous balance − withdrawal + deposit. For example, 11/3: $373.75 + $623.40 = $997.15. 11/12: $637.15 − $15.99 = $621.16.
Now suppose Jordan’s app shows $971.16 on 11/12. The difference is $971.16 − $621.16 = $350.00, exactly the rent check, which the landlord has not cashed yet. If Jordan spent from the app’s number, the check could later overdraw the account. Your register, not the app, tells you what is truly yours to spend.
Habit: record every transaction the day it happens, and once a month compare your register with your statement line by line.
Work these on your own, then open each answer to check yourself.
Starting balance $250.00. Then: deposit $180.25, debit card $42.10, ATM withdrawal $40.00, debit card $9.99. What is the ending balance?
Check your answer
$250.00 + $180.25 = $430.25; − $42.10 = $388.15; − $40.00 = $348.15; − $9.99 = $338.16.
Your register says $338.16 but the app says $383.16. You wrote a $45.00 check two days ago. What explains the difference?
Check your answer
$383.16 − $338.16 = $45.00: the check has not cleared yet. Use the register figure, $338.16.
Is a $3.00 out-of-network ATM fee recorded as an addition or a subtraction?
Check your answer
A subtraction: fees are withdrawals from your account.
Missouri standard PF.III.4.C: Payment Apps and Virtual Exchanges vs. Banks
Payment apps let you send money to a friend in seconds, and crypto exchanges let people buy virtual currencies online. Both are useful, but neither is the same as an account at an insured bank or credit union.
Payment apps (peer-to-peer)
- Benefit: fast, convenient transfers from your phone.
- Cost/risk: the CFPB says “FDIC insurance generally does not apply to money that sits in your payment app,” and if the company fails you “might not be entitled to get your money back.” Its advice: move money “right away from the payment app into an insured bank, credit union, or card account” (Consumer Financial Protection Bureau, consumerfinance.gov, “Is the money I keep in my payment app safe?”). Money you receive generally stays in the app until you move it (CFPB consumer advisory, June 1, 2023).
- Check yourself: read your app’s fee schedule to see whether it charges for instant transfers or card-funded payments.
Virtual currency exchanges
- No deposit insurance: the CFPB warns that if an exchange or wallet company fails, the government won’t cover your losses (CFPB consumer advisory on virtual currencies).
- Volatility: the CFPB noted that Bitcoin was down more than 70% as of October 3, 2022, from its November 2021 high (CFPB complaint bulletin, November 2022).
- Hidden cost, the spread: consumers complained of a large difference between the price to buy and the price to sell (CFPB bulletin, 2022).
Worked example: the cost of a spread (illustrative)
An exchange quotes a coin at $100.00 to buy and $97.00 to sell. You buy $200 worth: $200 ÷ $100 = 2 coins. If the price does not move at all and you sell right away: 2 × $97 = $194. You lost $200 − $194 = $6, or $6 ÷ $200 = 3%, just to get in and out.
Bottom line: use apps to move money, but keep money you need in an FDIC- or NCUA-insured account.
Work these on your own, then open each answer to check yourself.
A friend pays you $80 through a payment app. Where does the CFPB suggest the money should go, and why?
Check your answer
Move it into an insured bank, credit union or card account, because money sitting in the app generally is not FDIC insured.
Illustrative: an exchange quotes $50.00 to buy and $48.50 to sell. You buy $300 worth and sell immediately. How much do you lose, and what percentage?
Check your answer
$300 ÷ $50 = 6 coins; 6 × $48.50 = $291. Loss = $9, which is $9 ÷ $300 = 3%.
Give one benefit of a payment app and one cost compared with a bank account.
Check your answer
Benefit: fast, convenient transfers. Cost: balances generally lack FDIC insurance (and there may be fees for some transfer types).