THE VR SCHOOL
  • Schools & Districts
    • License the academy
    • Free program for your students
    • Request a demo
  • Catalog
    • AI & Data
    • Cybersecurity & Web
    • Programming
    • Health Science
    • All Guilds
    • All courses
  • Families
  • Accreditation
  • Log In
  • Request a demo
  • Home
  • Courses

RLP Personal Finance — Financial Decision Making

Curriculum

  • 8 Sections
  • 34 Lessons
  • Lifetime
Expand all sectionsCollapse all sections
  • Unit 1: Financial Decision Making
    5
    • 1.1
      The Role of Choice in Financial Decisions
      45 mins
    • 1.2
      Rational Decision-Making Process
      45 mins
    • 1.3
      Future Consequences of Financial Choices
      45 mins
    • 1.4
      Unintended Consequences
      45 mins
    • 1.5
      Unit 1 Quiz: Financial Decision Making
      45 mins
  • Unit 2: Earning Income
    4
    • 2.1
      Career Choices and Income
      45 mins
    • 2.2
      Forms of Compensation
      45 mins
    • 2.3
      Taxes and Deductions
      45 mins
    • 2.4
      Unit 2 Quiz: Earning Income
      45 mins
  • Unit 3: Buying Goods and Services
    4
    • 3.1
      Creating and Managing a Budget
      45 mins
    • 3.2
      Selecting Financial Institutions
      45 mins
    • 3.3
      Making Major Purchases
      45 mins
    • 3.4
      Unit 3 Quiz: Buying Goods and Services
      45 mins
  • Unit 4: Saving
    6
    • 4.1
      Setting Savings Goals
      45 mins
    • 4.2
      Interest and the Time Value of Money — Part 1
      45 mins
    • 4.3
      Interest and the Time Value of Money — Part 2
      45 mins
    • 4.4
      Savings Instruments
      45 mins
    • 4.5
      Retirement Planning
      45 mins
    • 4.6
      Unit 4 Quiz: Saving
      45 mins
  • Unit 5: Using Credit
    5
    • 5.1
      Understanding Credit and Credit Scores
      45 mins
    • 5.2
      Types of Credit and Debt
      45 mins
    • 5.3
      Managing and Avoiding Debt
      45 mins
    • 5.4
      Credit Rights and Responsibilities
      45 mins
    • 5.5
      Unit 5 Quiz: Using Credit
      45 mins
  • Unit 6: Protecting and Insuring
    3
    • 6.1
      Insurance Basics and Types
      45 mins
    • 6.2
      Identity Theft and Fraud Protection
      45 mins
    • 6.3
      Unit 6 Quiz: Protecting and Insuring
      45 mins
  • Unit 7: Financial Investing
    3
    • 7.1
      Investment Instruments
      45 mins
    • 7.2
      Risk and Return
      45 mins
    • 7.3
      Unit 7 Quiz: Financial Investing
      45 mins
  • Unit 8: Capstone & EOC Preparation
    4
    • 8.1
      Comprehensive Review
      45 mins
    • 8.2
      Financial Planning Capstone Project
      45 mins
    • 8.3
      EOC Assessment Preparation
      45 mins
    • 8.4
      Mock EOC Assessment
      45 mins

Creating and Managing a Budget

“`html
Buying Goods and Services

Creating and Managing a Budget

🕐 12 min read
The Big Question

Do you know exactly where your money goes each month—and are you in control, or is your money controlling you?
A stylized graphic representing a balance scale

Imagine starting your first job, feeling rich on payday—only to run out of money by the end of the month and have nothing saved. This is the reality for many, and it’s why creating and managing a budget is one of the most empowering financial moves you can make.

Meet Alex: Fresh out of school and excited about a new $3,200/month job, Alex is stunned to see only $127 left just before payday. Without a budget, the money just disappeared—and Alex has no idea how or where. Sound familiar?

Budget

A budget is a plan for your money—deciding in advance where every dollar should go so your spending matches your goals and priorities.
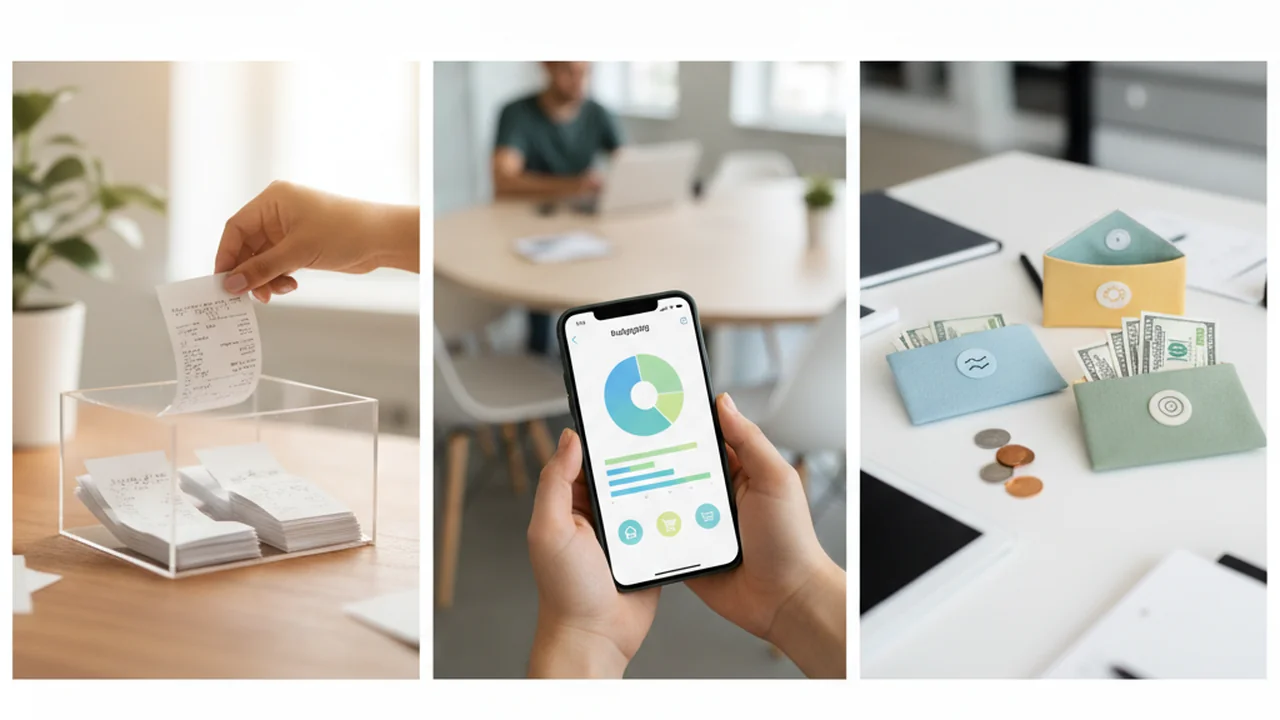
A multi-panel image showing three distinct methods for tracking spending
💡 Did You Know?

According to a 2023 Bankrate survey, only 41% of Americans use a budget or track their spending. Start now, and you’ll be ahead of the curve!

Income

Money you receive regularly, such as from a job, investments, or government benefits. Only count income you can count on reliably for budgeting purposes.
A person with a calm and focused expression is seated at a table, actively sorting and placing abstract coin or bill symbols into three distinct, open containers or sections

Understanding Income and Expenses

Your income is the money you receive—usually from a job (net paycheck), but it can also include consistent side jobs, support payments, or predictable investment returns.

Only budget income that’s reliable. Don’t count on gifts, one-off bonuses, or possible overtime that isn’t guaranteed.

Example: Anna consistently earns $400/month from her weekend job at a local café. She should include this in her budget. If she gets an occasional birthday gift from relatives, that money is a bonus—not part of her budget.

Expenses are what you spend money on. Some expenses stay the same every month—like rent or car payments (fixed expenses). Others change—like groceries or entertainment (variable expenses).

Financial coaches often recommend tracking your spending for an entire month. You might be surprised how much goes to dining out, subscriptions, or small impulse buys!

Which expenses in your life are “fixed” and which are “variable”? List three of each.

Income vs. Expenses: The Fundamental Equation

At its core, budgeting comes down to a simple equation:

Income - Expenses = Surplus or Deficit
  • Surplus: Income is greater than expenses—extra cash for savings or goals.
  • Balanced: Every dollar has a job. Income equals expenses (including savings).
  • Deficit: Expenses exceed income—this means you’re losing money, burning through savings, or going into debt.
❌ Common Misconception

Any money you receive can be included in your budget, even if it’s a one-time gift or an unguaranteed bonus.

✅ The Reality

Only reliable income—like your regular paycheck or consistent side hustle—should be budgeted. Irregular or uncertain income should not be counted until actually received.

Think of your last few months—did you spend more, less, or about the same as you earned? Why?

Flashcard

What is a fixed expense?

Tap to reveal
Answer

An expense that stays the same each month, such as rent, car payment, or a subscription.

Flashcard

Give an example of a variable expense.

Tap to reveal
Answer

Groceries, gas, entertainment, or clothing—amounts that can change from month to month.

Flashcard

What is the “Pay Yourself First” method?

Tap to reveal
Answer

Setting aside savings as your first “expense” each month, before paying for anything else.

Analyzing Spending Habits

Most people underestimate how much they spend, especially on small purchases, dining out, and subscriptions. Awareness is the first step to control.

If you buy a $5 coffee each day, that’s $150/month or $1,800/year—money that might be better spent on other priorities if you have bigger goals.

Four Ways to Track Your Spending

  • Receipt Method: Save and categorize receipts each week.
  • Bank/Credit Card Statements: Download and color-code your spending categories.
  • Budgeting Apps: Let digital tools like Mint or YNAB track and analyze your spending in real time.
  • Cash Envelope System: Use labeled envelopes of cash for categories like groceries or entertainment—when it’s gone, you stop spending.
Want to go deeper? The science behind tracking spending

Studies show people who track their spending—even for just a month—are more likely to stick to their budgets and reach savings goals. The act of recording purchases increases awareness and can cut spending by up to 20% in key categories.

⏱ 5 minutes
Activity: Your Spending Snapshot

Track your spending for the past week. Use bank statements, receipts, or a budgeting app.

  1. List every purchase you made last week and assign it to a category (e.g., food, transportation, entertainment).
  2. Total each category to see where your money is going.
  3. Identify one category where you could reduce spending next week.

After tracking your spending, what category surprised you the most? Why?

Common Spending Habit Pitfalls

  • Lifestyle Creep: As income goes up, spending rises too—so you never build savings.
  • Emotional Spending: Buying things to cope with stress or celebrate, often leading to regret.
  • Keeping Up with Others: Spending to match friends or social media trends instead of your own priorities.
  • Subscription Creep: Forgetting about unused subscriptions that keep draining your account.
  • Impulse Purchases: Buying things on a whim without comparing prices or considering need.

Awareness and regular audits (like a quarterly review of subscriptions) can help you plug leaks in your budget.

  • Understand the difference between income and expenses
  • Learned how to categorize spending as fixed or variable
  • Explored common pitfalls that derail budgets

Budgeting Methods: Choose Your Approach

1. 50/30/20 Method

  • 50% Needs: Rent, utilities, groceries, transportation, insurance
  • 30% Wants: Dining out, entertainment, hobbies, non-essentials
  • 20% Savings & Debt Payoff: Emergency fund, retirement, extra debt payments

Adjust these percentages to fit your real situation—maybe needs are higher in a big city, or you want to save more aggressively.

2. Zero-Based Budgeting

Every dollar you earn is assigned a job. At the end of the month, income minus all expenses equals zero—nothing is left unplanned.

3. Pay Yourself First

Automate your savings by setting it aside as soon as you’re paid. This makes saving a priority, not an afterthought.

4. Envelope System

Great for people who benefit from visual, tactile controls—once the envelope is empty, you stop spending in that category.

Fill in the blank

The rule suggests dividing your income into needs, wants, and savings/debt payments.

Which budgeting method do you think would be easiest for you to stick with—and why?

Key Takeaway

A budget is your roadmap for financial freedom—it helps you spend with intention, save for goals, and avoid debt.

“Without a budget, you’re driving financially with no map—you might end up somewhere, but probably not where you wanted to go.”

PROJECT CHECKPOINT 3.1 • 30–35 minutes

Project: Build a Zero-Based First-Year Budget

Course Driving Question: How can I build a realistic 10-year financial plan for my life after high school that can survive real-world trade-offs, setbacks, and opportunities?

Your project move: Give every dollar of monthly net income a job while reflecting realistic costs in your chosen Missouri community.

  1. Research or reasonably estimate housing, utilities, food, transportation, insurance, debt, savings, and wants.
  2. Create a monthly zero-based budget in which income minus expenses equals zero.
  3. Explain two trade-offs and identify which category you would change first if income fell by 10%.

Add to your Missouri Money Map: A cited monthly budget, category chart, and short trade-off note.

↻
Critique & Revision

Ask a partner to locate one missing or underestimated cost; revise the budget if needed.

Looking ahead, what is one financial goal you want to achieve in the next year, and how could a budget help you reach it?

0 words Take your time — depth matters more than length
Quick self-check

How confident are you that you can create a personal budget using one of the methods discussed?

Not yetVery confident
Key Takeaway

Tracking your income and expenses—and making small adjustments—can be the difference between financial struggle and success.

🔗
Connected Concept

Understanding net income (from paystubs) is crucial for building a realistic budget—review gross vs. net income if you need a refresher.

SHIFT

The Shift

  • A budget empowers you to decide where your money goes instead of wondering where it went.
  • Tracking and analyzing your spending helps you find opportunities to save—and avoid financial stress.
  • Choosing a budgeting method that fits your personality makes it easier to reach your financial goals.

Missouri standard PF.III.1.D: Budgeting for Charitable Giving and Its Tax Benefits

Many people include a giving line in their budget, the same way they plan for rent or savings. Planning gifts ahead keeps generosity from turning into a budget surprise, and it can also lower your taxes.

Charitable deduction

An amount you can subtract from your income for tax purposes because you gave it to a qualified organization. Lower taxable income means a lower tax bill.

What the IRS rules say

  • Who can receive deductible gifts: only qualified organizations, such as churches, most nonprofit charities, nonprofit schools and hospitals. Gifts to individuals are not deductible. You can check an organization with the IRS Tax Exempt Organization Search (IRS, Publication 526 and Topic 506, irs.gov).
  • New for 2026: beginning with tax year 2026, people who do not itemize may deduct up to $1,000 of qualifying cash contributions ($2,000 for married couples filing jointly). Noncash gifts such as donated clothing do not qualify for this deduction, and neither do cash gifts to donor advised funds or supporting organizations (IRS news release IR-2026-135, Nov. 10, 2026). Before 2026, you generally had to itemize on Schedule A to deduct gifts.
  • Records: for any cash gift keep a bank record or a written note from the charity showing its name, the date and the amount; for $250 or more you need a written acknowledgment from the organization (IRS, Topic 506).

Worked example (illustrative)

Maya budgets $25 a month to a Missouri food bank that is a qualified charity, paid by debit card. In 2026 she gives $25 × 12 = $300 in cash contributions. She does not itemize, and $300 is under the $1,000 limit, so she can deduct all $300. If each deducted dollar illustratively saved her 12 cents in federal income tax, her tax benefit would be $300 × 0.12 = $36. Her gift still costs her money, but $36 less than it otherwise would. Her bank statement serves as her record for each gift, since none reached $250.

⏱ 5 minutes
Self-check: Budgeting for Charitable Giving and Its Tax Benefits

Work these on your own, then open each answer to check yourself.

  1. Starting with tax year 2026, how much in cash gifts can a single person who does not itemize deduct?

    Check your answer

    Up to $1,000 of qualifying cash contributions ($2,000 on a joint return), per IRS IR-2026-135.

  2. Illustrative: Leo gives $40 a month in cash to a qualified charity in 2026 and does not itemize. How much can he deduct? Would donating an old coat count toward this deduction?

    Check your answer

    $40 × 12 = $480, which is under $1,000, so he can deduct $480. No: noncash gifts like a coat do not qualify for the non-itemizer deduction.

  3. You give $20 directly to a friend’s online fundraiser for their rent. Is that deductible? Why or why not?

    Check your answer

    No. Gifts to individuals are not deductible; the gift must go to a qualified organization.

Missouri standard PF.III.1.E: Prioritizing Expenses and Payment Due Dates

A budget says how much you will spend. A bill calendar says when. You can have enough money for the month and still pay a bill late if your paychecks arrive after the due date. Late payments can bring late fees, service shutoffs and, for credit accounts, damage to your payment history (Unit 5).

Due date

The last day a payment can be received without being late. Paying a few days early allows for processing time.

Step 1: Rank your expenses

  1. Housing (rent)
  2. Utilities and phone
  3. Food
  4. Transportation and required insurance
  5. Minimum payments on debts
  6. Savings
  7. Wants (streaming, eating out)

If money is short, protect the top of the list first, and contact a lender or landlord before a due date, not after.

Step 2: Match bills to paychecks (illustrative)

Sam is paid $700 on the 1st and $700 on the 15th.

BillAmountDuePaid from
Rent share$6001stPaycheck 1
Phone$5010thPaycheck 1
Streaming$1218thPaycheck 2
Car insurance$12020thPaycheck 2
Credit card minimum$3525thPaycheck 2

Paycheck 1: $700 − $600 − $50 = $50 left until the 15th. Paycheck 2: $700 − $12 − $120 − $35 = $533 left for groceries, gas and savings. Because the phone bill is due on the 10th, it must come from Paycheck 1, even though that leaves only $50 for two weeks. Seeing this in advance lets Sam set aside grocery money from Paycheck 2 for the first half of next month, or ask the phone company whether a later due date is available.

⏱ 5 minutes
Self-check: Prioritizing Expenses and Payment Due Dates

Work these on your own, then open each answer to check yourself.

  1. Put in priority order: streaming subscription, rent, credit card minimum payment, groceries.

    Check your answer

    Rent, groceries, credit card minimum payment, streaming subscription.

  2. Illustrative: you are paid $600 on the 1st and $600 on the 15th. Rent $500 is due on the 3rd, internet $60 on the 12th, and a $90 insurance bill on the 16th. How much is left from each paycheck?

    Check your answer

    Paycheck 1 covers rent and internet (both due before the 15th): $600 − $500 − $60 = $40. Paycheck 2 covers insurance: $600 − $90 = $510.

  3. Why can a person with enough monthly income still pay a bill late?

    Check your answer

    Because the timing is wrong: the paycheck may arrive after the bill’s due date. Matching bills to paydays fixes this.

Up Next Continue to Next Lesson →
“`

Leave a Reply Cancel reply

Unit 2 Quiz: Earning Income
Prev
Selecting Financial Institutions
Next

© 2026 The VR School | Career content by Wiley | Powered by Sejal Learning Systems.

Join free · Accreditation · Privacy Policy · Terms of Service

Modal title

Main Content