How much risk are you willing to take to achieve your financial goals—and how can you balance risk and reward to build wealth over time?
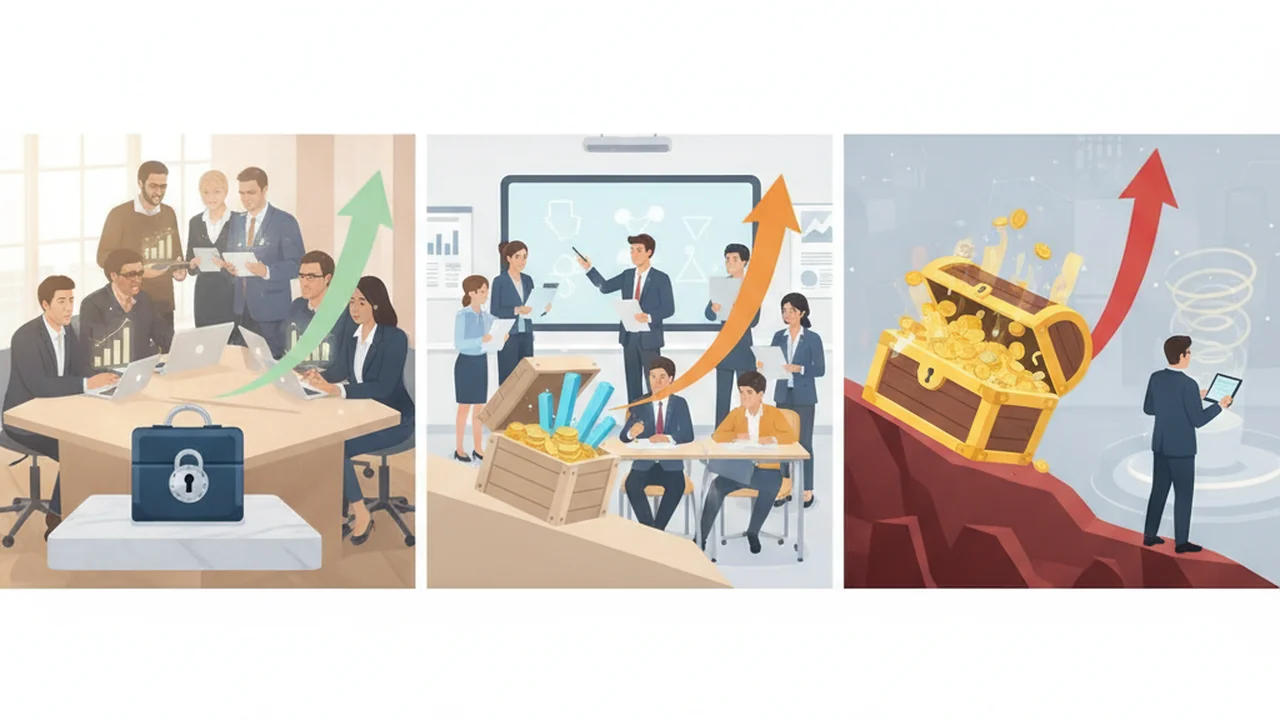
Introduction: The Risk-Return Reality Check
Meet Taylor, Jordan, and Casey—three Missouri State graduates who each made very different investment choices over 20 years. Their results show why understanding risk and return is essential for every investor.
Three Missouri State Graduates, Three Investment Strategies
All three graduated in 2004, age 22, and invested $500/month for 20 years. Here’s what happened:
- Taylor (“No Risk”): Chose a high-yield savings account. After 20 years, Taylor gained just $27,000—barely beating inflation.
- Jordan (“Moderate Risk”): Built a balanced portfolio with stocks and bonds. Jordan’s account grew by $227,000, even after a 30% drop in 2008.
- Casey (“Extreme Risk”): Tried to beat the market with penny stocks and day trading—but ended up losing $25,000 overall.
Higher expected returns require accepting higher risk, but excessive risk-taking often backfires.
The sweet spot for most investors is calculated, diversified, long-term investing—not chasing quick profits or avoiding all risk.
During the 2008 financial crisis, nearly all investments lost value—but those who stayed invested recovered and even grew their wealth by 2013.
Part 1: Understanding the Risk-Return Tradeoff
1.1: The Fundamental Principle
The principle that potential returns rise with increased risk—low-risk investments offer lower returns, while higher-risk investments may offer greater rewards (but less certainty).
Think of the spectrum:
- Low risk, low return: Savings accounts (1-2%)
- Moderate risk: Bonds (4-6%), balanced funds (6-8%)
- High risk, high return: Stock funds (8-12%), individual stocks, penny stocks (±50%+)
If you put your money in a savings account, you won’t lose it—but you might not keep up with inflation. Investing in stocks can offer much higher returns, but your account value will rise and fall along the way.
What is your comfort level with seeing your investment value fluctuate—would you rather play it safe, or accept some risk for better growth?
1.2: Expected Return vs. Required Return
The average return you anticipate earning over time, based on historical data and investment type.
The minimum return needed to justify taking on extra risk, usually calculated as risk-free rate plus a risk premium.
- Stocks (large-cap): 10-11% average annual return
- Bonds: 5-7% average annual return
- Savings accounts: 1-3% annual return
But remember: individual years can swing wildly! For example, the S&P 500 dropped -37% in 2008 but gained +32% in 2013.
- Risk and return are closely linked—higher potential rewards require higher risk.
- Historical averages hide the volatility of individual years.
1.3: Risk Tolerance
Your risk tolerance depends on your age, financial goals, and time horizon. Young investors with a long timeline can usually afford more risk than someone saving for a near-term goal.
- Long timeline = more risk tolerated
- Short timeline = less risk tolerated
- Stable finances = more risk tolerated
- Emotionally stable = more risk tolerated
- Knowledge/experience = more risk tolerated
Financial advisors use risk tolerance assessments to help clients find the right investment mix for their goals and personality.
Think of two different savings goals—how would your risk tolerance change for each?
Want to go deeper? The science behind this…
Behavioral economics shows that most people feel losses twice as intensely as gains. This “loss aversion” explains why many avoid investing in stocks—even when the long-term rewards are higher. Understanding your emotional reaction to risk can help you build better financial habits.
What is the risk-return tradeoff?
Tap to revealThe principle that higher potential returns require accepting higher risk—investors must balance risk and reward based on their goals.
What is diversification?
Tap to revealOwning a mix of different investments to reduce the impact of any single asset’s poor performance and lower overall risk.
What is your risk tolerance?
Tap to revealThe amount of risk you’re comfortable accepting, influenced by your goals, timeline, finances, and emotional stability.
Use these questions to figure out your own risk tolerance:
- If your portfolio dropped 20% in a month, would you buy more, hold steady, or sell?
- Are you investing for a long-term goal (20+ years), mid-term (10-20 years), or short-term (less than 5 years)?
- Is your primary goal maximum growth, balanced growth and safety, or preserving what you have?
- Based on your answers, would you rate your risk tolerance as high, moderate, or low?
Part 2: Types of Investment Risk
2.1: Market Risk (Systematic Risk)
The risk that affects the entire market, such as recessions, interest rate changes, inflation, political instability, or global events. This risk cannot be eliminated through diversification.
Why can’t diversification fully protect you from market risk?
2.2: Company-Specific Risk (Unsystematic Risk)
The risk that affects individual companies, such as poor management or scandals. This risk can be reduced or eliminated by diversification.
If you own shares only in Boeing, a major crisis can hurt your portfolio. But if you own an S&P 500 index fund, one company’s troubles barely affect you.
If you just buy lots of different stocks, you’ll never lose money.
Diversification lowers company-specific risk, but market risk and other factors can still cause losses. No investment is completely risk-free.
2.3: Interest Rate Risk
The risk that rising interest rates reduce the value of existing bonds, making them less attractive compared to new bonds with higher rates.
What happens to bond prices when interest rates rise—and why?
2.4: Inflation Risk
The risk that your investment returns don’t keep pace with rising prices, reducing your purchasing power over time.
How can inflation risk affect a retiree living on fixed income?
Project: Stress-Test Risk and Return
Course Driving Question: How can I build a realistic 10-year financial plan for my life after high school that can survive real-world trade-offs, setbacks, and opportunities?
Your project move: Test whether your investment plan still makes sense when markets fall or goals move closer.
- Write a risk-tolerance statement using goal, time horizon, financial capacity, and emotional comfort.
- Model a significant market decline and explain what you would hold, rebalance, or change—and why.
- Create a rule for reducing risk as the goal date approaches.
Add to your Missouri Money Map: A risk statement, stress-test table, and rebalancing rule.
Have a partner challenge whether your response is evidence-based or driven by fear or overconfidence.
Think about a financial goal you have (like saving for college or your first car). What kinds of risk are you most concerned about, and how would you balance risk and reward?
Missouri standard PF.VII.2.B: How Buyers and Sellers Move Prices and Returns
Stock prices are set in a market. The SEC explains: “The value of a stock is determined by the basic relationship between supply and demand.” If many people want a stock, the price rises; if few want it, the price falls (SEC, Key Points About Regulation SHO, sec.gov). Every trade needs a buyer and a seller who agree on a price.
Because your rate of return depends on the price you pay and the price you sell at, the actions of other buyers and sellers directly change your return.
(Ending price − purchase price + income received) ÷ purchase price.
Worked example (illustrative)
A company pays a $2.00 dividend per share each year.
- Buying when demand is low: at $40 a share, the dividend yield is $2 ÷ $40 = 5%.
- Buying after buyers bid the price up: at $50 a share, the same $2 dividend yields $2 ÷ $50 = 4%. More buyers made the investment more expensive and lowered the return for new buyers.
- Selling into demand: if you bought at $40, collected the $2 dividend, and buyers then pushed the price to $46, your one-year return is ($46 − $40 + $2) ÷ $40 = $8 ÷ $40 = 20%.
- When sellers outnumber buyers: if bad news makes many owners sell and the price drops to $35, the return is ($35 − $40 + $2) ÷ $40 = −$3 ÷ $40 = −7.5%.
The company paid the same dividend in every case. Only the crowd of buyers and sellers changed, and with it your return. This is why the same investment can be a good or poor deal depending on the price you pay.
Work these on your own, then open each answer to check yourself.
If many investors suddenly want to buy a stock, what usually happens to its price?
Check your answer
It rises, because demand is higher than supply.
Illustrative: you buy a share for $25, receive $1 in dividends, and sell for $23. What is your rate of return?
Check your answer
($23 − $25 + $1) ÷ $25 = −$1 ÷ $25 = −4%.
A $3 annual dividend stock rises from $60 to $75 because of heavy buying. What is the dividend yield for a new buyer at each price?
Check your answer
At $60: $3 ÷ $60 = 5%. At $75: $3 ÷ $75 = 4%.
Missouri standard PF.VII.2.C: Why Riskier Investments Like Penny Stocks Trade at Lower Prices
The SEC describes penny stocks as “low-priced shares of small companies,” which generally trade over-the-counter. They “may trade infrequently,” may be “impossible to accurately price,” and investors “should be prepared for the possibility that they may lose their whole investment” (SEC, Important Information on Penny Stocks, sec.gov). Investor.gov adds that many microcap companies are new with no proven track record.
Why risk pushes the price down
Buyers will only take on more risk if they expect to be paid for it. The way they demand that extra reward is by paying a lower price today for the same hoped-for future value.
Worked example (illustrative)
Two investments are each expected to be worth $110 in one year.
- Low-risk: buyers are satisfied with a 5% return, so they will pay $110 ÷ 1.05 = $104.76.
- High-risk: the company is small and unproven, so buyers demand a 25% expected return. They will pay only $110 ÷ 1.25 = $88.00.
Same hoped-for $110, lower price, because the outcome is uncertain. And for a penny stock the $110 is far from guaranteed: illustratively, a $0.50 share might double to $1.00 (+100%) or fall to $0.05 (−90%).
Low price is not the same as cheap. A $0.50 share is not a bargain compared with a $100 share; the price only tells you what buyers will pay given the risk. Thin trading also means a wide gap between the bid and the ask, which the SEC says can make a resale “very costly,” and you may not find a buyer at all.
Work these on your own, then open each answer to check yourself.
Why will buyers pay less today for a risky investment than a safe one with the same expected future value?
Check your answer
Because they want a higher expected return to compensate for the uncertainty, and paying a lower price is how they get it.
Illustrative: an investment is expected to be worth $60 in a year. What price would buyers pay if they want 20%?
Check your answer
$60 ÷ 1.20 = $50.00.
Name two risks the SEC lists for penny stocks.
Check your answer
Any two: they may trade infrequently (hard to sell), may be impossible to price accurately, have costly spreads, and you could lose your whole investment.
Which type of risk can be reduced or eliminated by diversification?
Diversification is your most powerful tool for reducing the risk of individual investments—spreading your money across different assets lowers the impact of any single company’s poor performance.
The Shift
- Understanding the risk-return tradeoff empowers you to make smarter investment choices based on your goals and timeline.
- Diversification reduces company-specific risk, but market risk and inflation still require careful planning.
- Assessing your own risk tolerance is key to building a portfolio that you can stick with—even in tough times.